Auto Insurances
Auto Insurances
Premium in the Fleet is Discussed with Driving Data
In a single vehicle, the decision may be made by price; In the fleet, the decisive factor is the damage frequency. The driver profile, intended use and previous damage file are a stronger argument than the premium at the renewal table.
It constructs car insurance, traffic and voluntary liability coverage according to your usage profile; We design the exemption and release structure together for fleets with high damage frequency.
- Insurance, traffic and fleet policies
- Exemption setup according to damage frequency
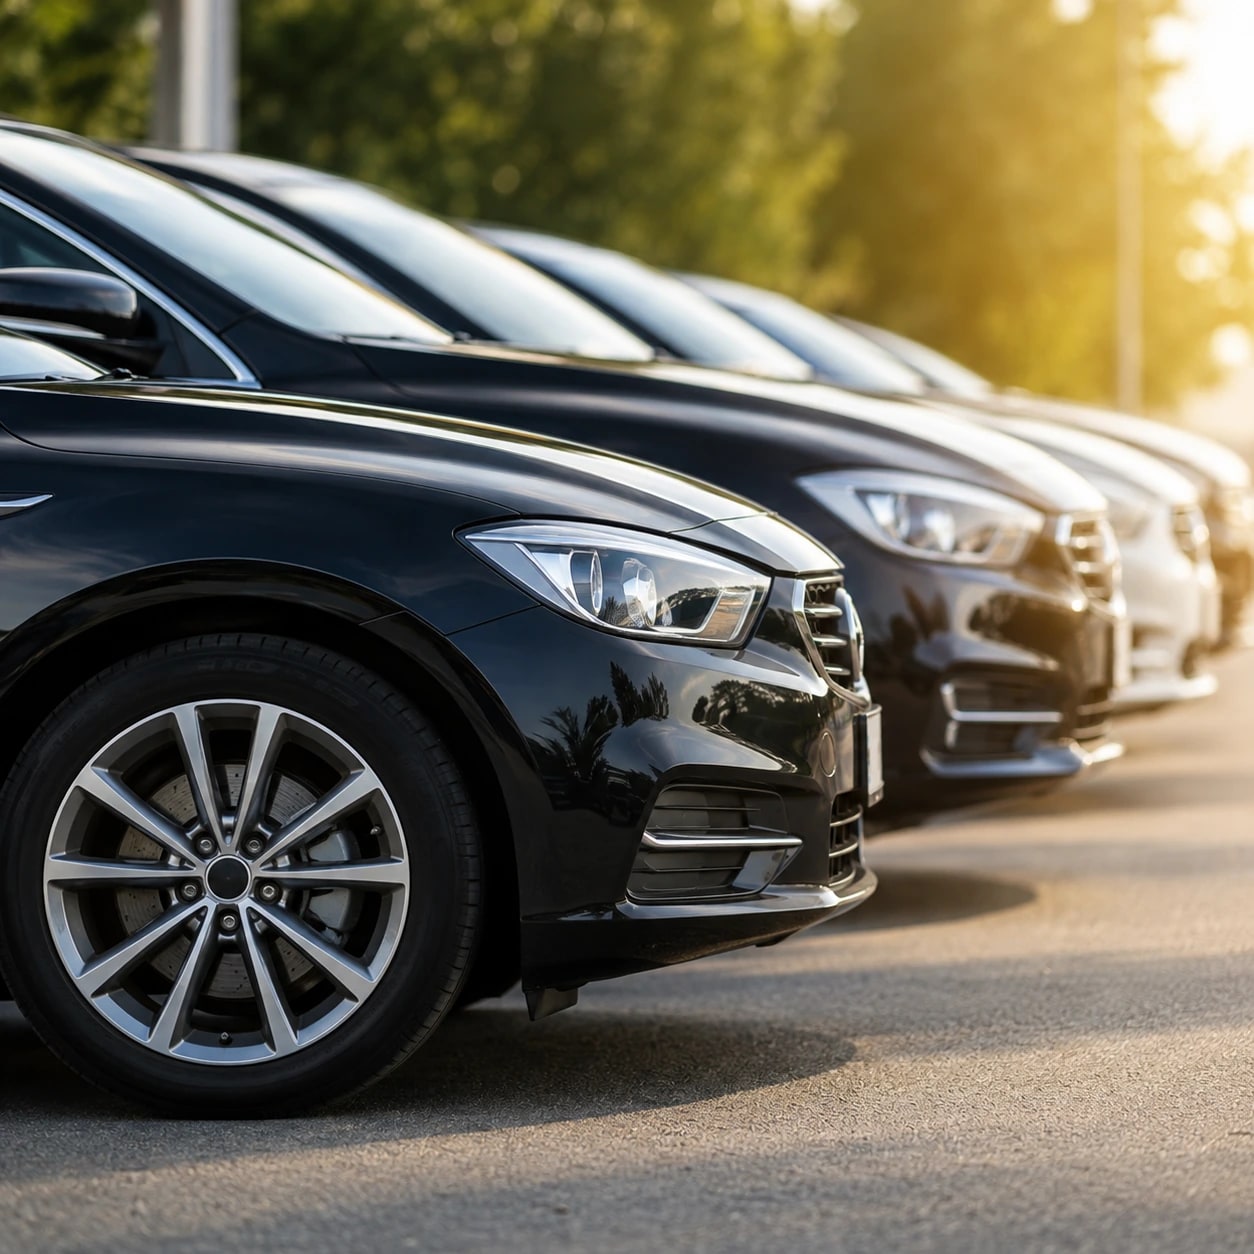
In fleet renewal, bargaining power is created not by bonuses, but by a well-kept damage file.
Scope
Coverage Scope
Extended insurance
All coverage for crash, crash, burn, theft and natural disaster.
Compulsory traffic insurance
Legal liability coverage for physical and material damages caused to third parties.
Fleet policies
A structure where vehicle entry and exit is managed from a single policy and prices are priced according to the usage profile.
Discretionary financial liability (IMM)
Additional protection for compensation claims exceeding mandatory traffic limits.
Personal accident seat insurance
Death and disability coverage due to accident for the driver, passenger and vehicle occupants.
International (Green Card) coverage
Mandatory liability coverage valid for vehicles going abroad.
Mandatory seat personal accident
Coverage required by legislation for passengers transported in road passenger transportation.
Key Risks
What We Watch in This Area
Damage Frequency
Small and frequent damages create more replacement costs than a single major damage.
Depreciation and Substitution
Replacement vehicle and loss of value claims will remain with you if they are not clearly included in the policy.
Driver Profile
Young drivers and high mileage directly affect coverage conditions.
How is it determined?
Data Determining Auto Coverage
- Vehicle value, brand-model information and model year
- Intended use: private, commercial, rental or passenger transportation
- Fleet size and average annual mileage per vehicle
- Driver age, driving license period and damage-free history
- Geography of use and need to go abroad
- Replacement vehicle with exemption preference and expectation of loss of value
FAQ
Frequently Asked Questions
The limits of compulsory traffic insurance may be insufficient, especially in cases of bodily harm. Otherwise, the amount remaining above the limit is covered by the vehicle owner's assets.
Vehicles joining and leaving the fleet are recorded in the policy with an addendum; The premium is calculated on a daily basis. We carry out this tracking on your behalf.
The current value at the time of damage is taken as basis, not the price stated in the policy. Therefore, correct entry of model year and equipment information directly affects the amount to be paid in case of destruction.
Instead of the step system in individual policies, the total damage/premium ratio of the fleet is taken as basis. In renewal, bargaining power is determined not by individual vehicles, but by the entire performance of the fleet.
Do You Have a Need in This Area?
Let's assess your risk together and build the coverage structure around your needs.