Fire Insurances
Fire Insurances
The real loss occurs not in the burning machine, but in the stationary line.
In a facility, the risk is not just in the building or machinery; is the interruption of the production chain. Even when physical damage is repaired, the income impact of the stopped activity continues.
It constructs the building, machinery, stock and income items not separately, but as a collateral set that complements each other; We review the price determination regularly.
- Fire, earthquake and additional guarantees
- Structure built with loss of profit
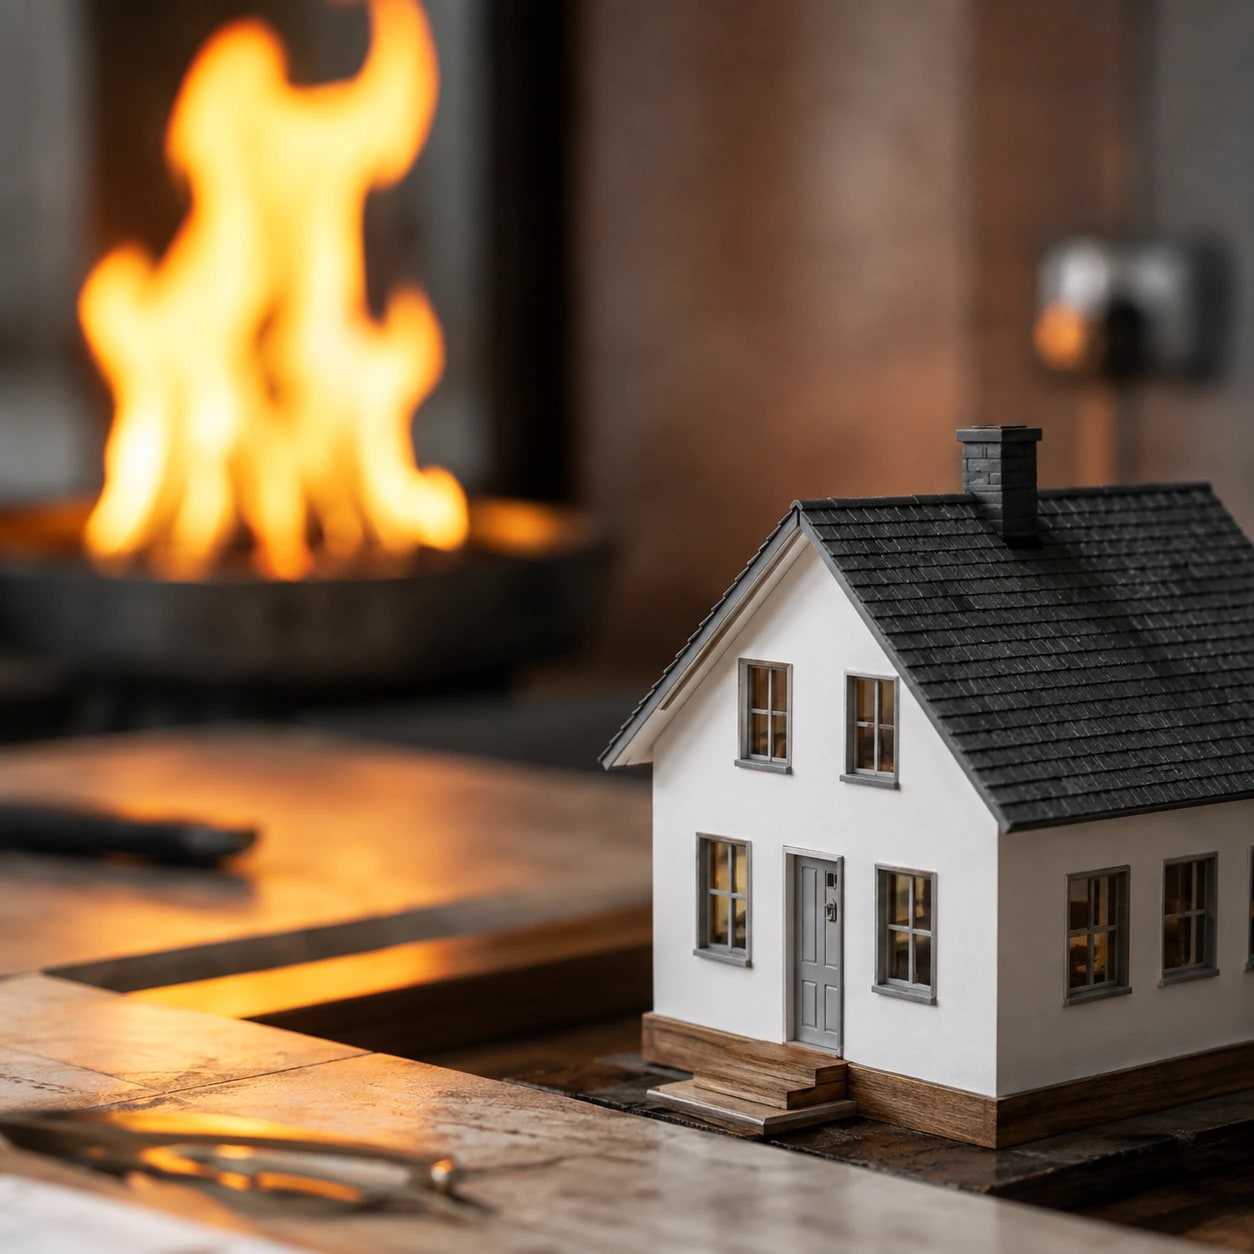
If the insurance amount remains below the actual value, the compensation decreases at the same rate. That's why price tracking is important.
Scope
Coverage Scope
Fire, lightning and explosion
The main coverage for physical damage caused by fire in buildings, machinery, fixtures and commodities.
Earthquake and volcano eruption
Establishing the limit and exemption structure for earthquake protection provided as additional guarantee.
Flood, flood and storm
Full of additional coverage for natural disasters, snow weight and landslide risks.
Theft and glass breaking
Commodity and fixture theft and fixed glass and facade breakage coverage.
Loss of profit (business interruption)
Gross profit and fixed expense loss of stopped production after a covered damage.
Debris removal and additional costs
Complementary items such as debris removal, temporary ground rent and expedited repairs.
Key Risks
What We Watch in This Area
Missing Insurance
If the price remains below the real value, the compensation is reduced proportionally.
Spare Parts Duration
As the lead time gets longer, choosing the right work interruption compensation period becomes critical.
Price Fluctuation
Stock and commodity prices change periodically; This is where the risk of underinsurance often arises.
How is it determined?
Data Determining Fire Coverage
- Building construction style, roof material and fire compartmentation
- Field of activity and flammable materials used in production
- Location: earthquake zone, flood basin, distance to fire station
- Extinguishing systems, detection infrastructure and hydrant capacity
- Storage layout, stack height and commodity turnover rate
- Time to return to full capacity in a business interruption scenario
FAQ
Frequently Asked Questions
If the insurance amount remains below the actual value at the time of damage, the compensation can be reduced by the same amount. For this reason, we recommend that the price determination be reviewed annually.
It is not automatically included; It is purchased separately as additional coverage. The limit and exemption structure is determined by region and building class.
The most frequently added ones are earthquake, flood, storm, domestic water, theft, glass breakage, loss of profit and debris removal. Which one is required is determined by location and activity structure.
The realistic time required for the facility to return to full capacity after damage is taken into account. In facilities with machines with long lead times, twelve months is often not enough.
Do You Have a Need in This Area?
Let's assess your risk together and build the coverage structure around your needs.